Category: Power & Energy Equipment

Korean makers of power grid and power generation equipment, explained from their regulatory filings.

  • HD Hyundai Electric: what it makes and how orders become revenue

    HD Hyundai Electric: what it makes and how orders become revenue

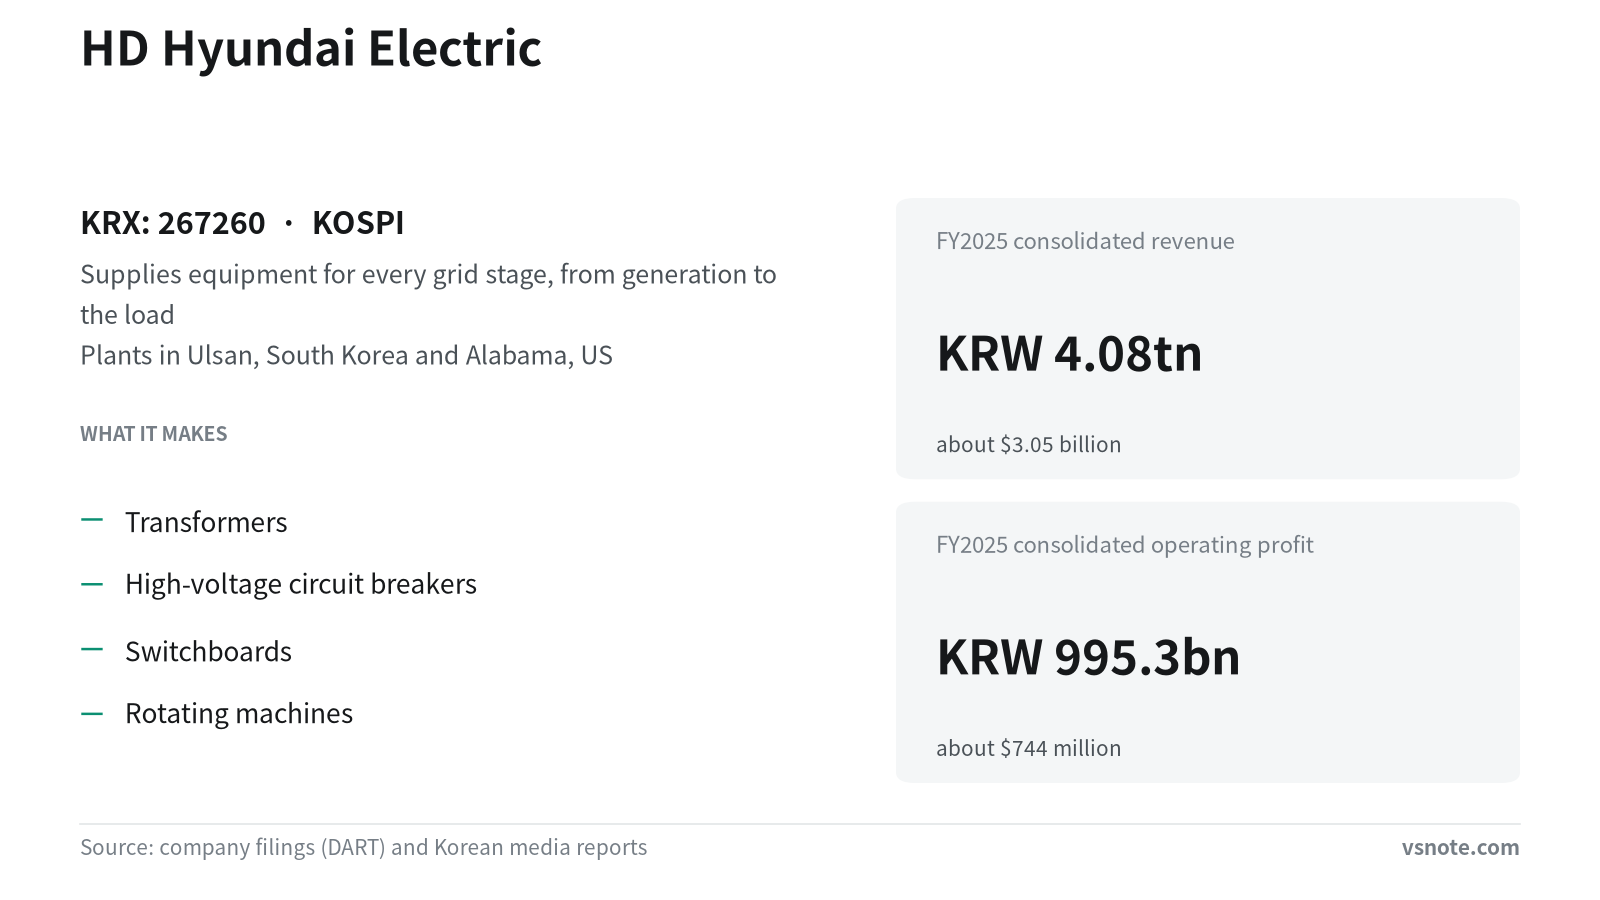
    Electricity made at a power plant goes through several stages before it reaches a factory, an office tower or a data center. Each stage needs heavy equipment. HD Hyundai Electric makes that equipment: transformers, circuit breakers, switchboards and rotating machines.

    The company does not sell electricity or collect power bills. The buyers are the parties that build power grids and large facilities, and they pay for the machines. The ‘HD Hyundai’ in its name is the name of a business group, and the company is one of that group’s affiliates.

    HD Hyundai Electric is listed on KOSPI, the main board of Korea’s stock exchange, under ticker 267260. Once it is clear that the company sells machines built to order, news about it falls into three kinds: who is buying, how orders already won turn into revenue, and where new demand comes from.

    HD HYUNDAI ELECTRIC CO.,LTD (에이치디현대일렉트릭) · KRX: 267260 · KOSPI

    Won amounts are converted at ₩1,338.2 per US dollar (Bank of Korea ECOS, KRW/USD base rate, 2026-09-11) for scale only.


    What stands between the power plant and the building

    Every national grid follows the same flow, the company’s annual report explains. Electricity is generated, transmitted, distributed and finally consumed by the end user, which is known as the load.

    The filing defines the electrical equipment industry as the business of making the machines needed to build and run that grid. HD Hyundai Electric supplies electrical equipment and energy solutions for all four stages.

    A parcel network gives a rough picture. Parcels move from trunk-route trucks to regional hubs to local delivery before they reach a door. HD Hyundai Electric is not the carrier in this picture. It builds the hubs and the sorting equipment.

    The comparison fails in two places. A hub can hold parcels before sending them on, but electricity has nowhere to be stacked up and must flow onward as soon as it arrives. And a transformer does not split a load into smaller boxes. It changes voltage, the pressure that pushes electricity along the line.

    The filings sort the company’s products by grid stage into power equipment, distribution equipment and rotating machines. Power equipment includes transformers, which raise or lower voltage, and high-voltage circuit breakers, which cut off the current.

    The equipment the company and its subsidiaries take orders for also includes switchboards and rotating machines. A switchboard is the cabinet that takes incoming power and splits it among the circuits inside a building. A rotating machine is equipment that does its work by spinning, driven by electricity.

    The company’s group ties show up in its disclosures. On August 14, 2026, it filed a notice on DART, Korea’s electronic disclosure system run by the Financial Supervisory Service, about changes to its trade in goods and services with affiliates under the same controlling shareholder.


    Who buys the equipment, and where it is made

    These are large machines. According to Korean media reports, the company’s plant in Ulsan, South Korea, builds large 500kV transformers, and each unit of the high-voltage equipment made there costs about KRW 10.0 billion (about $7 million).

    The company also manufactures in the United States. Its Alabama plant can reportedly make 105 power transformers a year, and a second plant there is expected to add about 50% to that capacity once it is finished.

    The buyers now go beyond grid projects. In July 2026, the company reportedly signed a long-term framework agreement with a global big tech company to supply power and distribution equipment for data centers in North America. Korean media describe direct contracts with big tech companies as a way for the company to reach more types of customer.

    Buyers in Korea matter too. Reports say more deliveries to semiconductor projects in Korea helped raise distribution equipment sales in the second quarter of 2026.

    In Korea, HD Hyundai Electric is grouped with Hyosung Heavy Industries and LS Electric as a domestic power equipment maker. The sources cited here do not compare the three companies or say what separates them, and they do not cover competitors outside Korea.


    When an order becomes revenue

    This equipment is ordered first, then built, then handed over. So three kinds of figure describe money at different points in time: revenue for a period, orders already in hand, and framework agreements stated as a ceiling.

    Start with full years. Korean filings number fiscal years in sequence, so FY2025 appears as the 9th period and FY2024 as the 8th. The figures below are consolidated, meaning they include subsidiaries, not just the parent company on its own (the separate, or standalone, figures).

    The annual report shows consolidated revenue of KRW 4.08 trillion (about $3.05 billion) in FY2025, up from KRW 3.32 trillion (about $2.48 billion) in FY2024. Operating profit rose from KRW 669.0 billion (about $500 million) to KRW 995.3 billion (about $744 million) over the same period, growing faster than revenue.

    Korean media reports say the company’s results have improved every year for five years, starting in 2021.

    Quarterly figures also come from media reports. For the second quarter of 2026, revenue was reportedly KRW 1.14 trillion (about $853 million) and operating profit KRW 287.0 billion (about $214 million), for an operating margin of 25.1%. For the second quarter of 2025, the same reports give revenue of KRW 906.2 billion (about $677 million) and operating profit of KRW 209.1 billion (about $156 million).
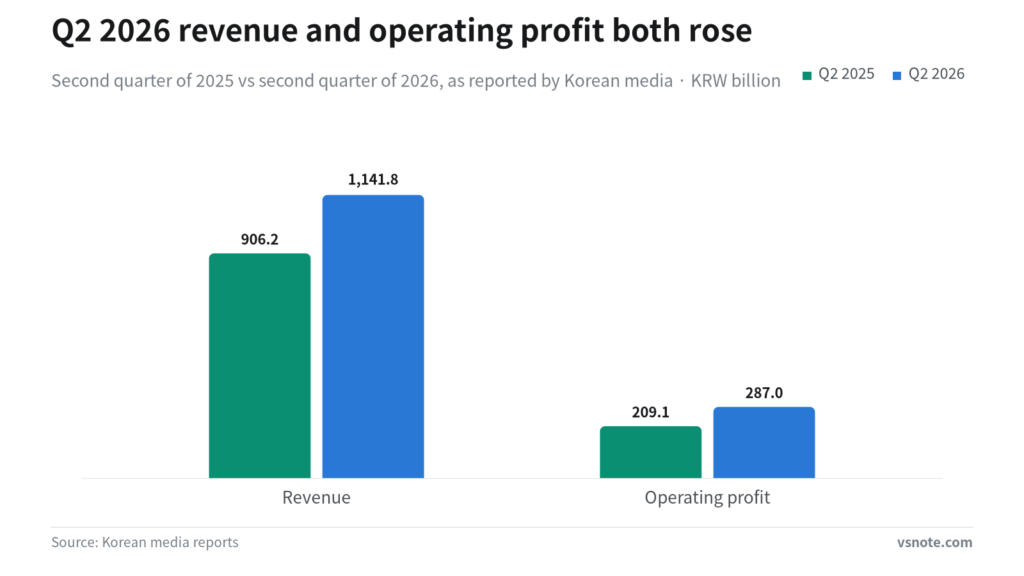
    Grouped bar chart comparing revenue and operating profit in the second quarter of 2025 and the second quarter of 2026.

    Distribution equipment brought in KRW 231.2 billion (about $173 million) of that second-quarter 2026 revenue.

    Order backlog is the value of orders received but not yet delivered and booked as revenue. Korean media reports put the backlog at $8.49 billion at the end of the second quarter of 2026. That figure is reported in US dollars, and the sources cited here give no exchange rate for it and no delivery schedule, so it cannot be set against won revenue to show how many years of work it covers.

    A framework agreement sets the terms for future purchases without fixing the actual orders. The July 2026 big tech agreement is reportedly worth up to KRW 1.12 trillion (about $838 million), and the actual orders are to come in stages through 2028, following data center construction schedules.

    That ceiling is neither revenue nor a single order. It is a maximum, and it becomes orders only as the buildings go up.


    Where new orders come from

    This industry depends on grids being built and expanded. Demand comes from facilities that need a new power supply: power plants, data centers and semiconductor facilities.

    A new power plant needs equipment at each stage between it and its users. According to Korean media reports, the Encinal gas-fired combined-cycle power plant in Texas, 6.3GW in total, is being pursued as the first project under Korea’s investment program in the United States. Reported plans for that first project also include building large nuclear power plants.

    The sources cited here do not connect HD Hyundai Electric to either of those projects.

    Data centers are a second source. Korean media report that demand for power equipment is rising, in part because more AI data centers are being built.

    Semiconductor facilities are a third, as the reported role of Korean chip projects in second-quarter distribution equipment sales shows.

    Views differ on whether this will last. According to Korean media reports, Kim Young-ki, the company’s president, has described its current growth as a structural ‘step’ rather than a lucky supercycle. That is the company’s own view.

    Calling it a supercycle carries the opposite assumption: that demand could fall back when the cycle ends. The sources cited here do not show which reading is right.


    Frequently asked questions

    Q. Is HD Hyundai Electric a power utility?

    A. No. It does not sell electricity. It makes transformers, circuit breakers, switchboards and rotating machines, and sells them to the parties that build power grids and large facilities.

    Q. How large is the data center agreement with a big tech company, and when does it become revenue?

    A. According to Korean media reports, the long-term framework agreement signed in July 2026 is worth up to KRW 1.12 trillion (about $838 million). Actual orders are to come in stages through 2028, following data center construction schedules, so the ceiling is not the same as revenue.

    Q. Where does the company make its equipment?

    A. Its Ulsan plant in Korea builds large 500kV transformers, and it also has a plant in Alabama. Korean media report that the Alabama plant can make 105 power transformers a year and that a second plant there is expected to add about 50% to that capacity once finished.

    Q. Where can I read the company’s own filings?

    A. Korean listed companies file on DART, the electronic disclosure system run by the Financial Supervisory Service. Annual reports number fiscal years in sequence, so FY2025 is the 9th period, and they report both consolidated and separate (standalone) figures.

    Q. Which Korean companies are grouped with it?

    A. Korean media group HD Hyundai Electric with Hyosung Heavy Industries and LS Electric as domestic power equipment makers. The sources cited here do not compare them.


    Sources

    • https://dart.fss.or.kr/dsaf001/main.do?rcpNo=20260316000940
    • https://dart.fss.or.kr/dsaf001/main.do?rcpNo=20260814002823
    • https://www.mk.co.kr/article/12144433
    • https://enter.etoday.co.kr/news/view/302298
    • https://blog.naver.com/ronto1/224408816328
    • https://blog.naver.com/bmchoice365/224408537619
    • https://blog.naver.com/mamie-reiki/224408801953
    • https://blog.naver.com/rs1717/224406516868
    • https://blog.naver.com/engineer_ji/224405574510
    • https://blog.naver.com/ezcomi1/224405594250
    • http://www.metroseoul.co.kr/article/20260909500019
    • https://www.ajunews.com/view/20260908153847082
    • https://blog.naver.com/handsomejuno/224406405806

    This article explains company filings and published figures for information only. It is not investment advice or a recommendation to buy or sell any security. Figures can change after publication — check the original filings before making decisions.
  • What Doosan Enerbility actually builds for a power plant

    What Doosan Enerbility actually builds for a power plant

    Doosan Enerbility, an affiliate of Korea’s Doosan Group, designs, fabricates and installs the large equipment that sits inside a power plant. Its shares are listed on the KOSPI, the main board of the Korea Exchange, under ticker 034020. (Korea’s second board is the KOSDAQ.)

    It does not sell to consumers. Its buyers are the organisations that build power stations — in Korea, the company’s own filings measure its domestic position against equipment ordered by Korea Electric Power Corporation, Korea Hydro & Nuclear Power and independent power producers, and it also works for owners abroad.

    The useful way to hold the company in mind is not “a nuclear company” but a made-to-order workshop for very heavy things: the party that designs the plant and the party that cuts the metal are not the same, and the day a contract is signed is not the day the piece is handed over. That gap is why order headlines and the income statement do not move at the same speed.

    DOOSAN ENERBILITY CO., LTD. (두산에너빌리티) · KRX: 034020 · KOSPI

    Won amounts are converted at ₩1,338.2 per US dollar (Bank of Korea ECOS, KRW/USD base rate, 2026-09-11) for scale only.


    Which part of a power plant the company makes

    The company’s annual report describes a business that designs, manufactures and services power generation equipment, including nuclear and combined-cycle plants, and that also takes on EPC work — contracts in which one company handles engineering, procurement of materials and construction as a single package.

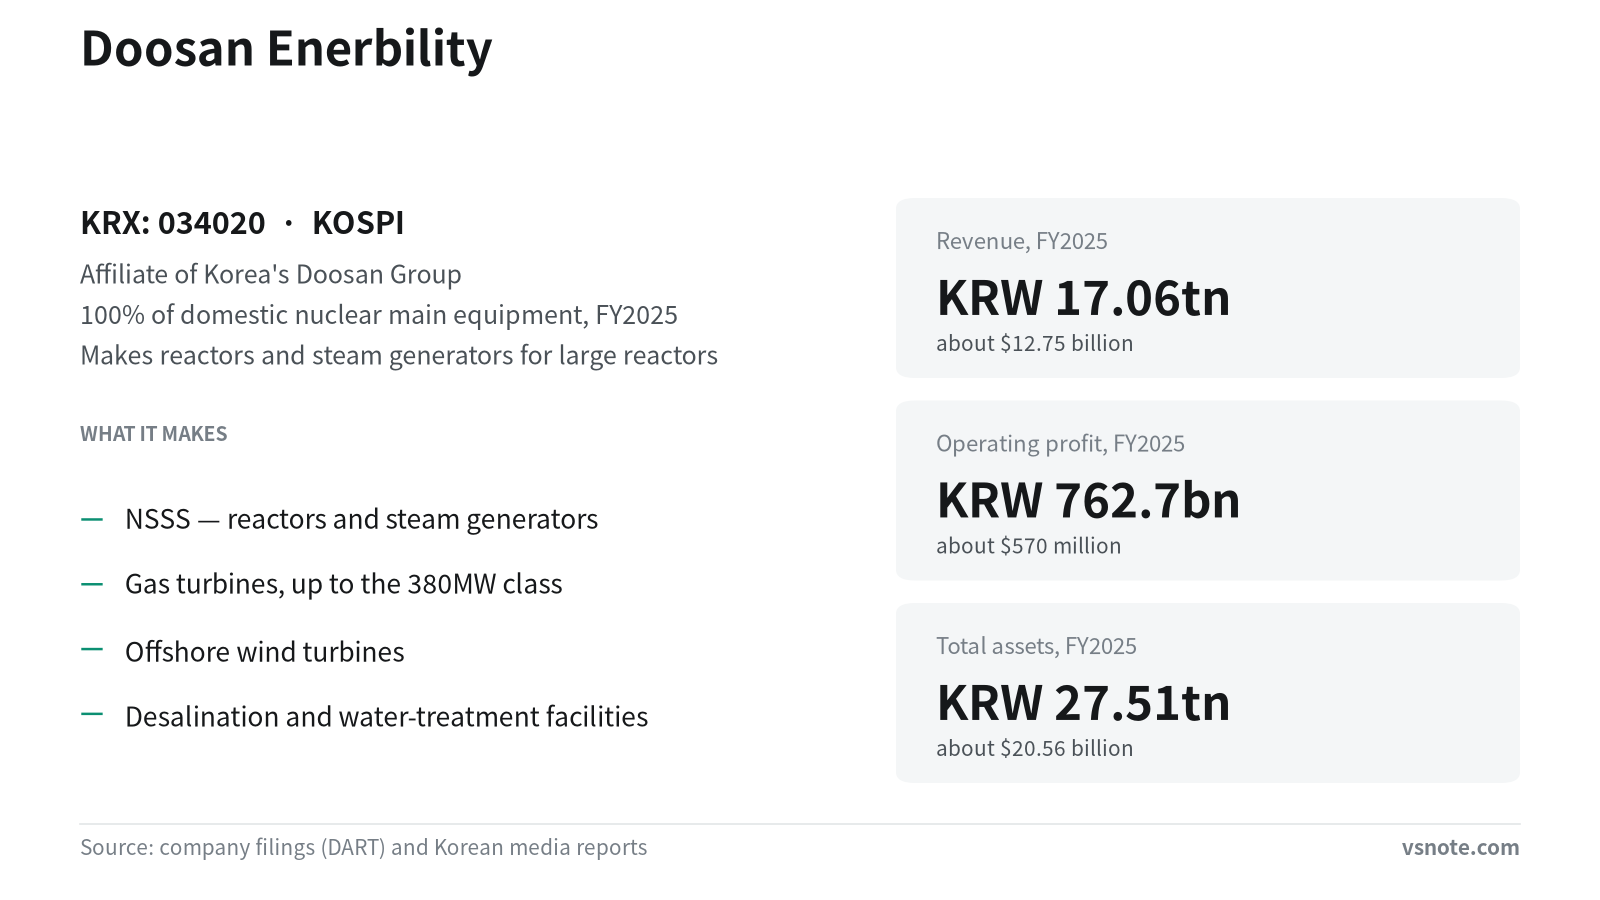
    The items listed for the business are NSSS (the reactor and the steam-producing equipment at the heart of a nuclear plant), BOP (everything apart from that core equipment — the auxiliary systems that make the plant actually run), turbines, desalination and water-treatment facilities, castings and forgings, and plant installation.

    Castings and forgings are a business in their own right: the company produces basic materials by casting and forging, which is the starting point for the heaviest components. It also builds renewable-energy equipment including offshore wind turbines.

    In nuclear specifically, the equipment industry is the business of producing and supplying a plant’s principal apparatus — reactors, steam generators and the like, often grouped as “main equipment.” The company is described as holding the technology and the production facilities to fabricate reactors and steam generators for large reactors. It does not follow from any of this that it designs reactor types; it makes the hardware.

    Outside nuclear, the company developed its own large gas turbine for power generation and has built a product line running from small to large units. Korean media accounts describe the first gas turbine built in Korea as Doosan’s.

    According to Korean media reports, its plant business spans three things at once: manufacturing plant equipment, providing plant services, and plant engineering and construction. In wind, it is reported to take part across the value chain — turbine supply, project development, equipment, EPC and maintenance.

    One name-level distinction is worth fixing early, because the news flow blurs it. TerraPower, NuScale Power and X-energy appear in stories about this company as counterparties it has built cooperative relationships with — they are partners, not parts of it.


    Two market-share numbers, measured with two different rulers

    Korean filings label fiscal periods by count rather than by calendar year, so the annual report speaks of the 61st, 62nd and 63rd fiscal years. With a December year-end, those are FY2023, FY2024 and FY2025. In FY2025, the company’s disclosed share of the domestic nuclear main-equipment market was 100%.

    That was not a one-period result: the filing shows the same 100% for FY2023, FY2024 and FY2025 alike.

    The overseas figure sits in the same disclosure and looks nothing like it. For FY2025, the company’s overseas nuclear market share is given as 3.0%.

    The two numbers are not in conflict, because they are not measured the same way. The domestic share counts main equipment ordered by Korea Electric Power Corporation, Korea Hydro & Nuclear Power and independent power producers. The overseas share is calculated on new nuclear units by country over roughly the past ten years, including units under construction.

    Read alone, the first number says “sole supplier at home” and the second says “small presence abroad.” Both are true of different questions, and the company’s disclosure keeps them side by side. Market share is also broken out by segment — power generation equipment and desalination equipment are disclosed separately.

    Korean media coverage places the company in the domestic nuclear value chain as a reactor and main-equipment firm, and separately as an SMR firm. It is reported to be able to supply main equipment for large reactors, and to produce gas turbines in the 380MW class.


    What it takes to make the same things

    If one company supplies all the domestic nuclear main equipment, the obvious question is what keeps the position. The annual report answers it directly, in the company’s own words: the core competitive factors in power plant EPC, equipment and services are product technology, competitive manufacturing capability, and the supply chain that supports it.

    Nuclear equipment carries a very high quality requirement. Meeting it, the filing says, requires design, materials, welding, machining and assembly capability — a set of skills that has to exist together, not separately.

    The broader power equipment industry divides into nuclear plant equipment, combined-cycle equipment and offshore wind turbines. Of these, the nuclear equipment industry is described as having large ripple effects on upstream and downstream industries, requiring long-term technology development and large-scale investment, and being fostered strategically at the national level.

    Put together, the dividing line in this business is capability rather than price: whether a shop can make the part at all. The filings cited here do not name any domestic or overseas competitor, so who else clears that bar is not something this material settles.

    The same capability framing extends to newer work. The company is developing technology to burn hydrogen mixed into gas turbine fuel and to extend that toward firing on hydrogen alone.


    Revenue up, profit down

    The figures that follow are consolidated — parent and subsidiaries combined. Korean issuers also file separate, or standalone, statements covering the parent alone; the two sets are different numbers, and everything here is the consolidated set.

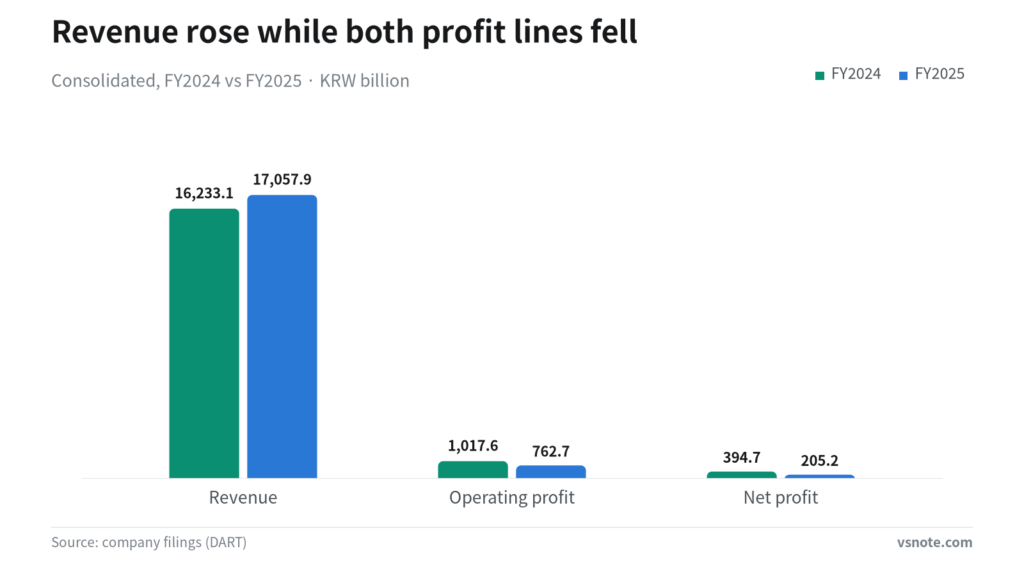
    Consolidated revenue in FY2025 was KRW 17.06 trillion (about $12.75 billion), up from KRW 16.23 trillion (about $12.13 billion) in FY2024.

    Operating profit moved the other way, from KRW 1.02 trillion (about $760 million) in FY2024 to KRW 762.7 billion (about $570 million) in FY2025. Net profit fell from KRW 394.7 billion (about $295 million) to KRW 205.2 billion (about $153 million) over the same two periods.

    Grouped bar chart comparing consolidated revenue, operating profit and net profit for FY2024 and FY2025.

    Set those earnings against the balance sheet and the shape of the business shows. Total consolidated assets were KRW 27.51 trillion (about $20.56 billion) at the end of FY2025, against KRW 26.31 trillion (about $19.66 billion) a period earlier — a very large asset base carrying a comparatively thin profit.

    This is where the workshop image breaks down. A workshop with no orders can simply fold up the bench; a company of this kind carries its plants and heavy machining capacity whether or not the order book is full.

    The filings cited here do not give the company’s explanation for the decline in profit, so the cause is not something this article can supply.

    The direction did not hold. According to Korean media reports, first-half 2026 revenue rose about 8% against the same period a year earlier and operating profit rose by more than 32%. Those reports point to the half-year report as of June 2026 filed with DART, Korea’s electronic disclosure system run by the Financial Supervisory Service, where Korean issuers lodge their statutory filings.

    Two years in one direction and a half-year in the other: one or two years of figures do not settle what this company earns across a cycle.


    What stands between an order and an earnings line

    The bridge between the news flow and the income statement is the order backlog: work that has been contracted but not yet built and handed over, and therefore not yet recognised as revenue. According to Korean media reports, the backlog stood at KRW 26.40 trillion (about $19.73 billion) at the end of the first half of 2026.

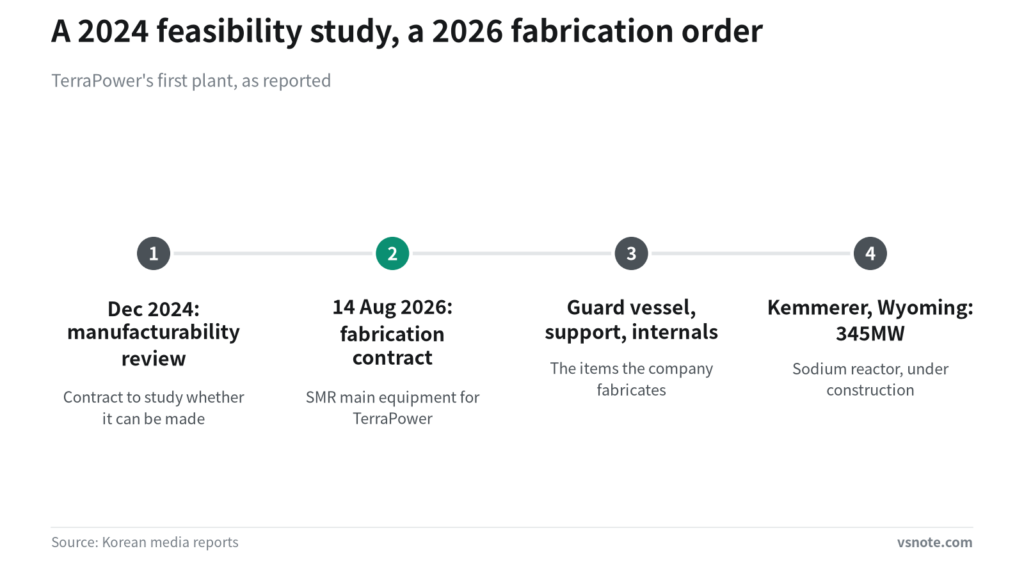
    Recent contracts show the timeline involved. Korean media reports say that on 14 August 2026 the company signed a contract with TerraPower to fabricate main equipment for an SMR — a small modular reactor, built in factory-made modules and shipped to site rather than assembled wholly in place.

    The same reports describe the scope: equipment for TerraPower’s first plant, under construction in Kemmerer, Wyoming, in the United States. The items are the reactor guard vessel, the reactor support structure and the reactor internals, applied to TerraPower’s sodium reactor. The Kemmerer project is reported at 345MW.

    That contract did not appear from nowhere. The cooperation is reported to have begun in December 2024 with a contract to review whether the first unit’s key equipment could be manufactured at all — a study, years before the fabrication order.

    Four-stage sequence running from the December 2024 manufacturability review to the Kemmerer plant the equipment is destined for.

    Two other contracts are reported in the same window: on 21 August 2026, a construction contract for the Misfah combined-cycle power plant in Oman, and on 27 July 2026, a contract to supply key materials for units 5 and 6 of the Laiyang nuclear plant in China.

    For all three, the sources cited here give neither contract values nor when any of the work would be recognised as revenue. That last step — from a signed order to a line in the accounts — is the one the reader has to leave open.

    On where demand is said to be coming from, Korean media reports say the Encinal gas-fired combined-cycle plant in Texas, at 6.3 to 6.4 gigawatts, was selected as the first project under Korea’s investment programme in the United States. The project is reported to be staged: about 1.4GW of gas turbine capacity by 2030, then sequential expansion toward 4.9GW of high-efficiency combined-cycle capacity once demand and economics are confirmed.

    Writing about that project, Han Seung-hun, an analyst at Shinhan Securities, said in a report that if commercial operation of 1.4GW by 2030 is the target, ordering is likely to move early and to centre on gas turbines, which take a long time to procure. That is a statement about the project’s procurement sequence, not about any company’s order book.

    Beyond Encinal, Korean media reports say a plan to build eight large nuclear plants in the United States is under review as a follow-on to the same investment programme. It is reported as under consideration; nothing in the material cited here says it has been decided.


    Frequently asked questions

    Q. Is Doosan Enerbility a nuclear company?

    A. Only in part. Its annual report lists nuclear main equipment alongside turbines, BOP — the auxiliary systems outside the reactor island — desalination and water-treatment facilities, castings and forgings, and plant installation, plus EPC work where it handles engineering, procurement and construction together. It also makes offshore wind turbines and developed its own large gas turbine for power generation.

    Q. Its filing shows 100% domestic nuclear main-equipment share and 3.0% overseas. How can both be true?

    A. They measure different things. The 100% figure — reported for FY2023 through FY2025 — counts main equipment ordered by Korea Electric Power Corporation, Korea Hydro & Nuclear Power and independent power producers. The 3.0% figure, for FY2025, is calculated against new nuclear units by country over roughly the past decade, including units under construction.

    Q. When a new order is announced, does it show up in revenue?

    A. Not at signing. Contracted work that has not yet been built and delivered sits in the order backlog, which Korean media reports put at KRW 26.40 trillion (about $19.73 billion) at the end of the first half of 2026. For the 2026 contracts reported in Korean media — TerraPower, Oman and China — the sources cited here give no contract values and no revenue-recognition timing.

    Q. What is the company’s relationship to TerraPower, NuScale Power and X-energy?

    A. They are counterparties, not parts of the group. Korean media reports describe cooperative relationships built with NuScale Power and X-energy, and a contract signed with TerraPower in August 2026 to fabricate the reactor guard vessel, reactor support structure and reactor internals for its sodium reactor at Kemmerer, Wyoming.

    Q. Where do these numbers come from, and which set should I read?

    A. The financial and market-share figures here are from the company’s annual report; the company files with DART, Korea’s electronic disclosure system run by the Financial Supervisory Service, and is listed on the KOSPI under ticker 034020. Note two Korean conventions: fiscal periods are numbered rather than named by calendar year (here the 63rd is FY2025), and issuers file both consolidated statements and separate, parent-only statements — every figure in this article is consolidated.


    Sources

    • https://dart.fss.or.kr/dsaf001/main.do?rcpNo=20260320001246
    • https://www.doosanenerbility.com/en
    • https://blog.naver.com/iriad80/224407711147
    • https://blog.naver.com/salimhae/224407696851
    • https://blog.naver.com/jony97/224407004282
    • https://blog.naver.com/ryuhongreoul/224406923554
    • https://blog.naver.com/warmblack2024/224407142872
    • https://blog.naver.com/onulsdaily/224407596295
    • https://www.businesspost.co.kr/BP?command=article_view&num=446804

    This article explains company filings and published figures for information only. It is not investment advice or a recommendation to buy or sell any security. Figures can change after publication — check the original filings before making decisions.